-
Brandon Thompson - CEO - Commercial and Personal Insurance Agent -

Kirk Reisner - CFO - Commercial Insurance Agent -
Jenessa Figinsky Commercial Account manager Springfield, MO -
Tyler Hunter - Licensed Producing Agent, Oak Grove, MO
What Is the Difference Between General Liability and Professional Liability Insurance?
General liability insurance typically covers claims involving bodily injury or damage to someone else’s property, such as a customer slipping at your business or an employee accidentally damaging a client’s home. Professional liability insurance, also called errors and omissions (E&O), addresses claims that a mistake, incorrect advice, or failure to deliver a professional service caused a customer financial harm. For mechanics, plumbers, and electricians, specialized coverage may be available through contractors E&O or similar policies. Many businesses need both types of protection because general liability typically excludes professional errors, and coverage for faulty work varies by policy.
What Does Professional Liability Insurance Cover?
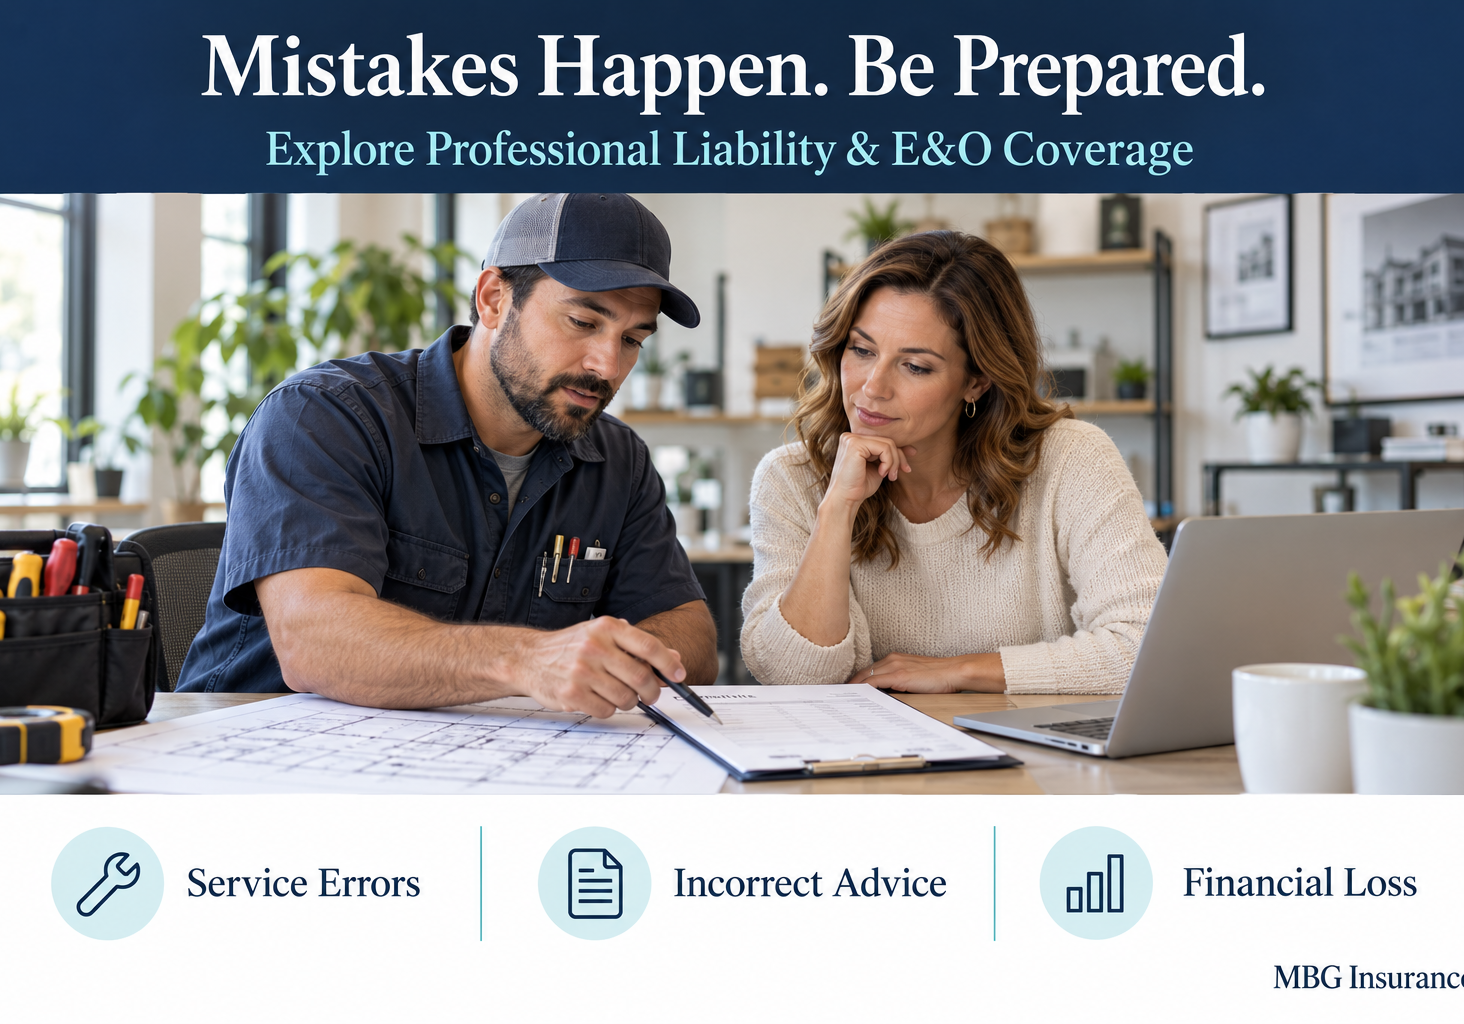
Professional liability insurance helps protect your business when a customer claims that your advice, services, or professional mistakes caused them financial harm. Depending on your industry and policy, coverage may include:
Errors and omissions:
Mistakes or overlooked details in the services you provide.
Negligence:
Claims that your work failed to meet the standard of care expected in your profession.
Incorrect advice or recommendations:
Guidance that leads to a customer’s financial loss.
Failure to deliver services:
Allegations that you did not perform agreed-upon services properly.
Legal defense costs:
Attorney fees and other covered defense expenses, even when a claim is unfounded.
Settlements and judgments:
Payments for covered claims, subject to your policy’s limits and terms.
For mechanics, plumbers, and electricians, specialized E&O coverage may address certain claims involving mistakes in their services or workmanship. Coverage for correcting your own work, replacing defective parts, or damage resulting from faulty work varies by policy, so it is important to review what your coverage actually includes.
Who Needs Professional Liability Insurance?
Any business that provides advice, specialized services, or professional expertise should consider professional liability insurance. Customers may seek compensation if they believe a mistake or oversight caused them financial harm—even when you believe your work was done correctly.
Businesses that may need coverage include:
- Doctors and other healthcare providers
- Attorneys and law firms
- Insurance agents and real estate professionals
- Accountants, bookkeepers, and consultants
- Architects, engineers, and technology professionals
- Certain contractors and service businesses
Coverage should match the services you perform. Medical malpractice, traditional professional liability, and contractors errors and omissions policies address different exposures. The Hartford Professional Liability Page.
Do Mechanics, Plumbers, and Electricians Need Errors and Omissions Coverage?
Mechanics, plumbers, and electricians should consider whether specialized errors and omissions coverage could help fill gaps in their business insurance. A mistake in diagnosing a problem, selecting materials, or completing an installation can create expenses that general liability insurance may not cover.
For plumbers and electricians, contractors E&O coverage may help address certain claims involving faulty workmanship, defective materials, or errors in completed work. Mechanics should ask about coverage specifically designed for automotive repair operations. These policies differ, so coverage for repairing your own work, replacing parts, and a customer’s resulting financial loss must be reviewed carefully.
What Does Professional Liability Insurance Not Cover?
Professional liability insurance protects against specific risks associated with your services, but it does not cover every business loss. Common exclusions or limitations include:
- Intentional wrongdoing or fraud
- Bodily injury and property damage: Often excluded under traditional professional liability policies, although specialized policies may provide coverage.
- Employee injuries: Generally addressed through workers’ compensation insurance.
- Cyber incidents: May require separate cyber liability coverage.
- Contractual guarantees: Promising a particular result or assuming liability beyond your normal legal responsibility may fall outside coverage.
- Known claims or earlier errors: Prior knowledge provisions and retroactive dates can restrict coverage.
The cost to redo defective work or replace faulty parts is also policy dependent. Professional liability insurance should not be treated as a warranty or a guarantee of customer satisfaction.
How Much Does Professional Liability Insurance Cost?
Professional liability insurance costs depend on the services your business provides and the potential financial consequences of a mistake. An independent consultant, a medical practice, and an electrical contractor can have very different coverage needs and premiums.
Factors that can affect your price include:
- Your industry and the services you provide
- Business revenue and number of employees
- Claims history
- Coverage limits and deductible
- Business location
- Policy features and coverage for prior work
At MBG Insurance, we help businesses in Missouri and Arkansas explore coverage options that fit their operations, contractual requirements, and budget. A quote based on your actual services provides a more useful estimate than a general industry average.
How Do Claims-Made Professional Liability Policies Work?
Many professional liability policies are written on a claims-made basis, meaning coverage depends on when a claim is first made against your business. Many also require the claim to be reported to the insurer within a specified period. The alleged mistake generally must have occurred on or after the policy’s retroactive date, if one applies.
For example, a mistake made during an earlier year may qualify for coverage when a claim arrives later, provided you maintained appropriate coverage, preserved the applicable retroactive date, and met the policy’s reporting requirements.
Before changing carriers, canceling coverage, or retiring, review how claims involving past work will be handled. An extended reporting period, often called tail coverage, may give you additional time to report qualifying claims involving earlier services. It does not cover new work performed after the policy ends.
How Much Does Professional Liability Insurance Cost?
The cost of professional liability insurance varies based on your industry, the services you provide, your business size, claims history, and the coverage limits you choose. How the coverage is offered can also affect the price. Some insurance carriers include certain professional liability or errors and omissions coverage within a business insurance package, while others offer it as an optional endorsement for an additional premium. Other businesses need a standalone policy tailored to their profession.
At MBG Insurance, we help you review available options and understand what each includes. Coverage can differ significantly between a package endorsement and a standalone policy, so comparing protection is just as important as comparing price.
Why Choose MBG Insurance?
MBG Insurance helps business owners understand what they are buying and how their policies work together.
As an independent agency, we work with multiple insurance companies and review options based on your operations and coverage needs. Our team can help you evaluate:
- Whether your services are accurately described.
- Liability limits and important exclusions.
- Customer and contractor insurance requirements.
- Additional insured endorsements.
- Coverage changes as your business grows.
- Options for related business insurance.
Our Springfield and Oak Grove, Missouri, and Bentonville, Arkansas, offices work together to serve businesses across both states.
Frequently Asked Questions About Professional Liability Insurance
Helpful Articles from the InsuranceNerds!

"Kirk and the Crew at Millennium have gone above and beyond to help me find the right insurance for my rental properties. They always take the time to explain the options of each company they bring to the table. I highly recommend MBG Insurance for all your insurance needs."
JW Delong
"Can't say enough good things about Tyler and MBG Insurance. I reached out to 4 insurance brokers, he was by far the quickest and most knowledgeable about the industry. Also gave me recommendations and discounts that I was not aware of. In the end I was able to lower my insurance premium by 17%."
Derek Lee
Explore our commercial insurance options for additional protection for your business.
Coverage is subject to the issued policy’s terms, conditions, exclusions, and available limits. Eligibility and requirements vary by carrier.
Updated October 19, 2026