What is an umbrella policy?
A personal umbrella policy is extra liability insurance that kicks in when the limits on your home, auto, or other policies run out. Think of it as a second layer of protection: if you're found responsible for an accident, injury, or property damage that exceeds your existing coverage, your umbrella policy picks up where those policies leave off — often adding $1 million or more in additional liability protection.
Umbrella coverage isn't just for people with expensive homes or cars. It's designed for anyone whose assets — savings, investments, home equity, future earnings — could be at risk in a lawsuit. If you have a net worth of $1 million or more, a single serious claim (a car accident, an injury on your property, even a defamation lawsuit) could easily exceed the liability limits on your standard policies. Without an umbrella policy, your personal assets become the next target to satisfy a judgment.
Umbrella policies also often cover claims that standard policies exclude or limit, such as libel, slander, and certain lawsuits, and they typically cost far less than people expect — often just a few hundred dollars a year for $1 million in coverage. At MBG Insurance, we shop more than 20 top-rated carriers to build umbrella coverage that matches your actual risk and net worth, giving you real protection without overpaying.
What policies can an umbrella policy extend over?
An umbrella policy typically extends liability coverage over these underlying policies:
Homeowners/Renters Insurance — Adds liability protection beyond your home or renters policy's limits for injuries to others on your property, dog bites, or damage you cause to someone else's property.
Auto Insurance — Extends bodily injury and property damage liability limits from your auto policy, covering serious at-fault accidents where damages or medical costs exceed your car insurance limits.
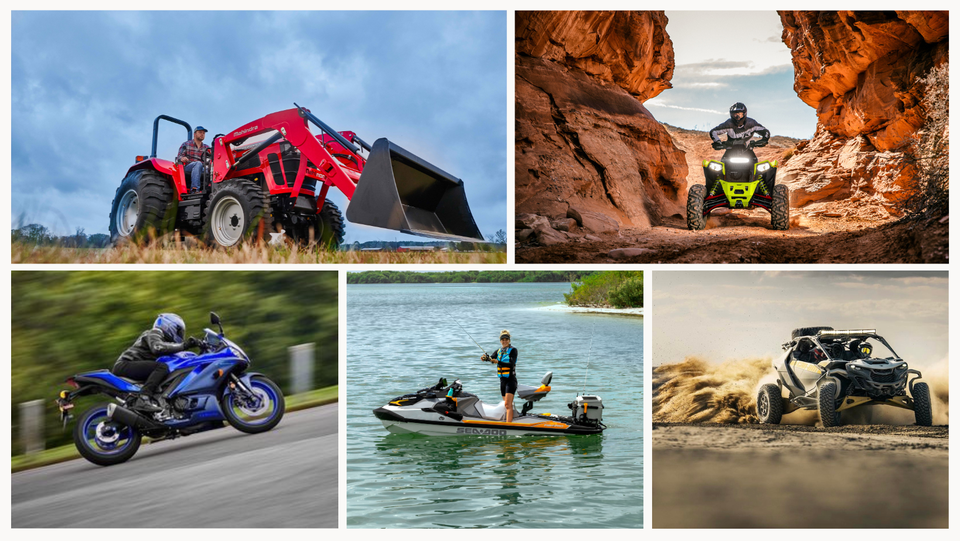
Boat/Watercraft Insurance — Covers liability from boating accidents beyond your watercraft policy's limits.
Motorcycle/RV Insurance — Same concept — extra liability protection above what your recreational vehicle policy provides.
Landlord/Rental Property Insurance — For clients who own rental properties, an umbrella can extend liability coverage across those policies too, which matters if a tenant or visitor is injured.
What affects the cost of an Umbrella Policy?
Several factors affect the price of a personal umbrella policy:
Coverage limit selected — Most umbrellas start at $1 million and go up in $1 million increments (up to $5 million, $10 million, or more with certain carriers). Higher limits cost more, though the jump from $1M to $2M is often surprisingly small compared to the cost of the first $1M.
Number of underlying exposures — How many homes, vehicles, watercraft, or rental properties you're covering affects the price. More exposures generally mean higher premium, since there's more potential for a claim.
Number of vehicles and drivers — More vehicles, teenage drivers, or drivers with violations/accidents on their record increase risk and cost.
Claims and driving history — A history of liability claims, at-fault accidents, or DUIs raises the price (and can even affect eligibility).
Rental properties or extra liability exposures — Owning rental property, having a swimming pool, trampoline, or dog breed with bite history can increase cost since these raise liability risk.
Underlying policy limits required — Some carriers require higher minimum limits on your home/auto liability before they'll write the umbrella, which can shift cost between the underlying policy and the umbrella itself.
Business or board involvement — If someone serves on a nonprofit board, owns a side business, or has other liability exposures outside personal life, that can affect pricing or require additional coverage.
Despite all these factors, umbrella policies are usually inexpensive relative to the protection they provide — often $200–$800/year for the first $1 million in coverage.